Market Recap (8/30/26)
Market Recap of the Week of Aug 23, 2026 - Aug 30, 2026
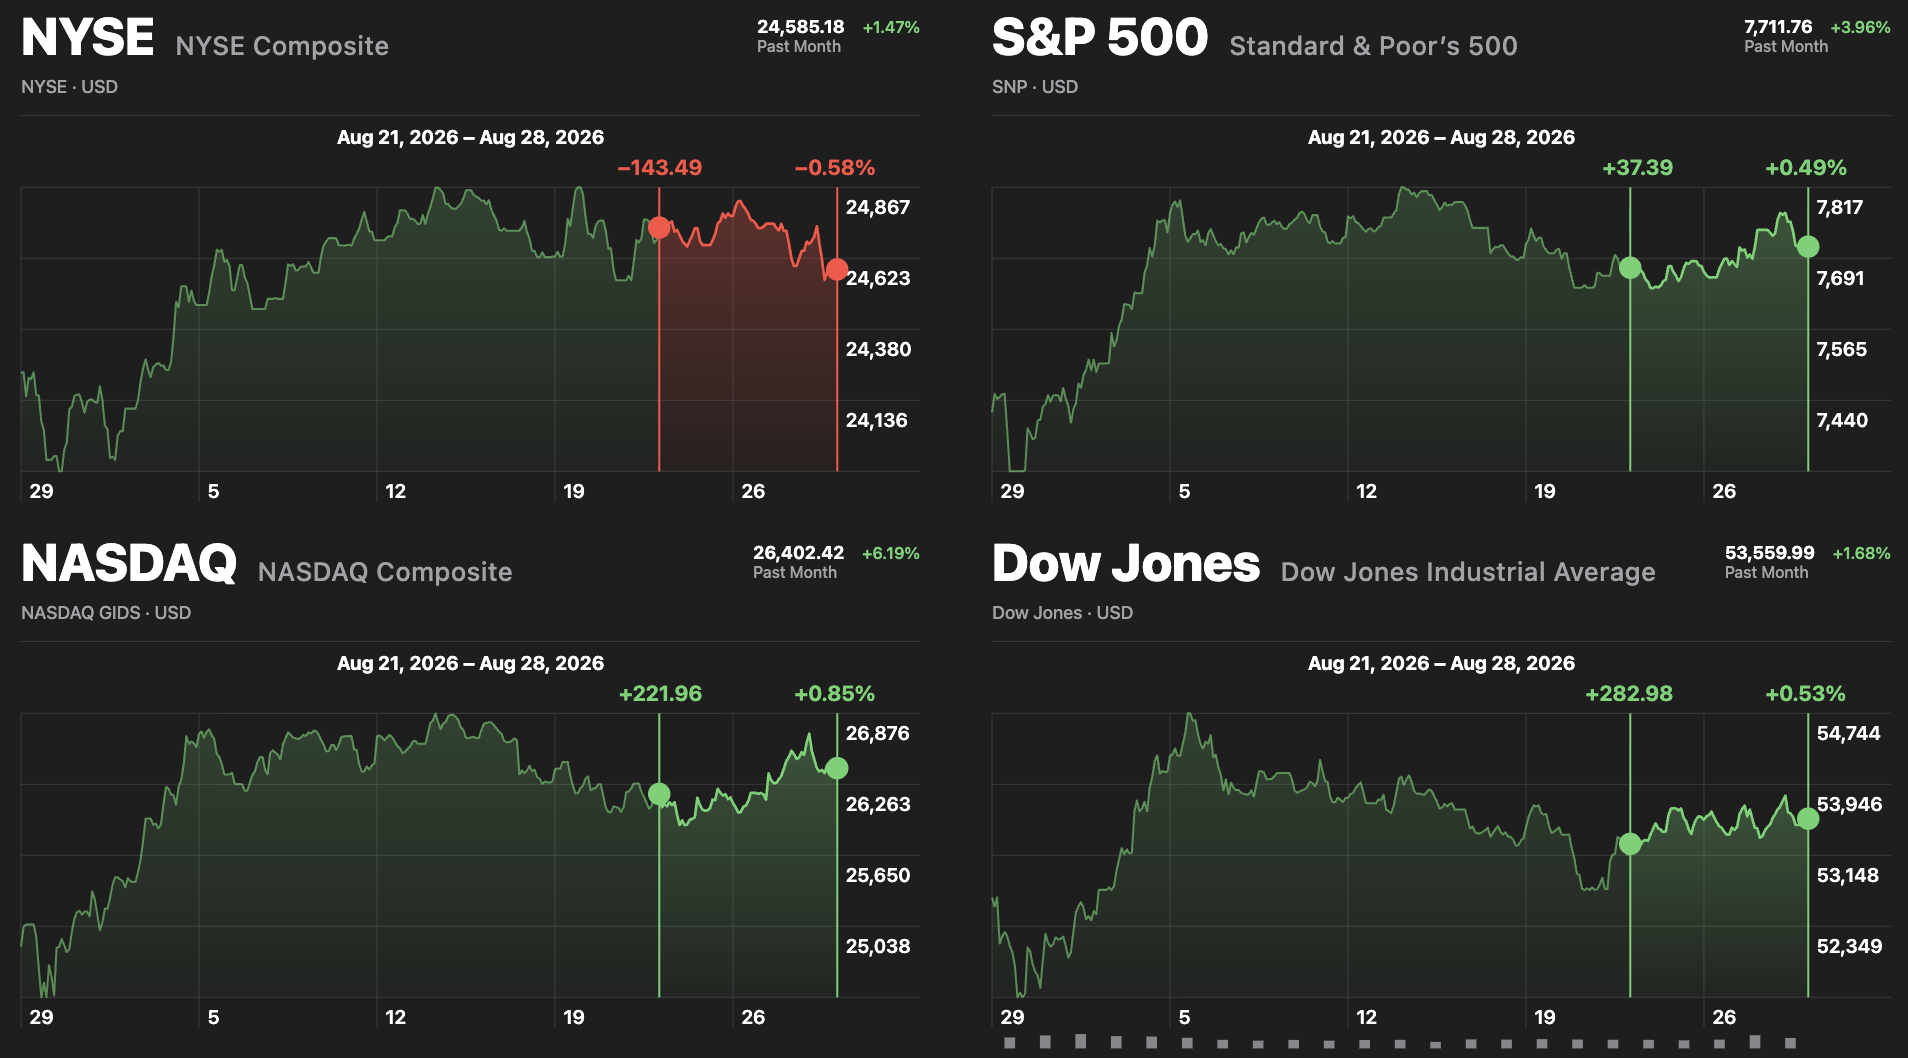
Source: Apple Stocks Application
Overall Market Trends:
The market faced mixed results last week, with three of the four major indices finishing in the green. The New York Stock Exchange Composite (NYSE) fell 143 points (-0.58%), while the S&P 500 climbed 37 points (+0.49%), the NASDAQ Composite advanced 222 points (+0.85%), and the Dow Jones Industrial Average posted a weekly gain of 283 points (+0.53%). These results were largely influenced by strong artificial intelligence-related earnings, the latest inflation data, and shifting interest rate expectations following Federal Reserve Chairman Kevin Warsh’s speech at Jackson Hole.
Stocks faced mixed results during Monday’s trading session as a sell-off in technology companies pushed the S&P 500 and NASDAQ lower while the Dow managed to eke out a small gain. Chip stocks led the decline, with Micron Technology (NASDAQ: MU) plummeting nearly 6% while Advanced Micro Devices (NASDAQ: AMD) and Broadcom (NASDAQ: AVGO) fell more than 3% and 2%, respectively. Seagate Technology (NASDAQ: STX) also tumbled 6.5%. Treasury yields declined after it was reported that the Treasury Department may use its General Account to fund a larger debt-buyback operation. However, this was not enough to offset the weakness throughout the technology sector. President Trump also announced that tariffs on automobiles, automotive parts, and steel imported from Canada would increase to 50% beginning on January 1, 2027, adding to the uncertain sentiment. The announcement followed the breakdown of recent trade negotiations between the two countries.
The market rebounded on Tuesday as falling Treasury yields and a rally throughout the semiconductor industry outweighed weaker consumer confidence and trade concerns. The 10-year Treasury yield fell more than 7 basis points to 4.625%, extending Monday’s decline, while West Texas Intermediate crude futures dropped more than 3%. Nvidia (NASDAQ: NVDA) rose 2% ahead of its earnings report, snapping a seven-day losing streak. Advanced Micro Devices and Micron Technology followed suit, climbing nearly 5% and 2.5%, respectively. Consumer companies, however, struggled after Dick’s Sporting Goods (NYSE: DKS) collapsed 30% following disappointing earnings, marking its worst trading session on record. Walmart (NASDAQ: WMT) and Target (NYSE: TGT) also fell 1% and nearly 4%, respectively. The Conference Board’s Consumer Confidence Index declined by 0.8 points to 89.4, lower than the 90.2 estimate. Canada also announced retaliatory tariffs against the United States, stating that it would match the recently announced 50% levies dollar for dollar. However, these concerns were not enough to reverse the semiconductor-backed rally.
The market finished Wednesday relatively unchanged after the latest Personal Consumption Expenditures Price Index report showed that inflation remained elevated. The PCE price index, which is closely monitored by the Federal Reserve, came in slightly hotter than expected for July while core PCE matched estimates. The overall index increased 0.2% during the month. Treasury yields remained relatively stable after the 10-year yield fell nearly 8 basis points during Tuesday’s session. Meta Platforms (NASDAQ: META) rose roughly 1% after reaching a settlement with state attorneys general over allegations that its social media platforms had harmed younger users. Investors largely remained on the sidelines as they waited for Nvidia’s earnings report and Federal Reserve Chairman Kevin Warsh’s upcoming speech.
Stocks soared on Thursday following strong earnings reports from Nvidia and several other prominent technology companies. Nvidia skyrocketed nearly 9% after beating estimates and forecasting robust revenue growth. The company’s second-quarter revenue more than doubled, while its fiscal 2028 revenue growth was projected to reach 70%, far exceeding analysts’ expectations of 44%. This news sent other semiconductor companies higher, with Broadcom and Intel (NASDAQ: INTC) rising 4.5% and 4%, respectively. Salesforce (NYSE: CRM) surged more than 22% after its revenue exceeded expectations. Cybersecurity stocks also experienced massive gains as demand relating to agentic AI continued to expand. Okta (NASDAQ: OKTA) soared more than 28% while CrowdStrike (NASDAQ: CRWD) and Palo Alto Networks (NASDAQ: PANW) jumped roughly 21% and 13%, respectively. These results helped the technology sector, S&P 500, and NASDAQ post their strongest sessions since August 4.
The market pulled back slightly on Friday after Federal Reserve Chairman Kevin Warsh expressed continued concern over inflation during the central bank’s annual symposium in Jackson Hole. Warsh acknowledged that recent inflation reports had come in better than expected but stated that they did not show that underlying inflation trends had meaningfully improved. He reiterated that inflation remained above the Federal Reserve’s 2% target. The estimated odds of a September interest rate hike surged from 35.4% to 57.5% following his remarks. Semiconductor companies, including Nvidia and Intel, declined and weighed on the NASDAQ. Gap (NYSE: GAP) jumped roughly 13% after announcing a new chief executive for its struggling Old Navy brand, while Marvell Technology (NASDAQ: MRVL) tumbled more than 10% after releasing disappointing guidance for its current-quarter gross margin.
Source: CNBC (Consumer News and Business Channel)
Past Earnings Report:
This Week in Crypto
Live Crypto Markets:
Looking Towards the Future
Upcoming Important Economic Events:
Monday: Markets closed for Labor Day Holiday
Tuesday: Consumer Credit
Wednesday: No events scheduled
Thursday: Weekly jobless claims • Producer Price Index (PPI) • Core PPI
Friday: Consumer Price Index (CPI) • Core CPI
Future Earnings Reports: